
Buy your business premises through your super.
Your self-managed super fund can borrow to buy commercial property, including the premises your own business trades from. Your business pays market rent to your fund instead of a landlord. We find the lenders that do SMSF commercial lending and set up the loan with your accountant and adviser.
Get in touch
Be your own landlord.
When your SMSF owns your premises, the rent your business pays goes into your own retirement savings. You also get security of tenure, with no outside landlord ending the lease or lifting the rent.
An SMSF loan broker for commercial property knows which lenders accept fund borrowers, what they need to see, and how the structure has to be set up. As your local mortgage broker in Albury & Wodonga, we check the fund against lender policy and flag gaps before you apply. If you are comparing this with borrowing against property you already own, we can also talk you through a home equity loan.
We work alongside your accountant or financial adviser, so the lending fits the strategy they recommend.
Loan Street Finance provides credit assistance only. We are not licensed to give financial product advice, which includes advice on setting up an SMSF, whether your fund should borrow, or whether a property suits your fund's investment strategy. Before going ahead, speak with a licensed financial adviser and your accountant.
The information on this page is general only and reflects superannuation rules as at November 2026. These rules can change.
How SMSF Commercial Loans Work
An SMSF commercial property loan follows a structure set out in superannuation law. Moneysmart's guide to SMSFs and property is a useful grounding. These are the parts that matter most:
Limited Recourse Borrowing Arrangement
The fund borrows through a limited recourse borrowing arrangement (LRBA). If the loan defaults, the lender can only claim the property bought, not the fund's other assets.
Holding Trust
The property sits in a separate holding (bare) trust until the loan is repaid. It must be in place before contracts are signed, as errors here are costly to fix later.
Business Real Property
Commercial property used wholly and exclusively in a business is known as business real property. This is the key exception that lets your fund lease the premises to your own business, provided rent is at market rate and paid on time.
Repayments From Rent and Contributions
Rent from the tenant and contributions to the fund service the loan, not your personal income. Lenders look closely at whether that cash flow covers repayments and costs.
Why SMSF Lending Is Now Commercial Only
Since 10 August 2026, new SMSF property loans can only be used to buy business real property, broadly land and buildings used wholly and exclusively in a business. In practice, that means SMSF lending today is commercial lending, and it's the only kind of SMSF loan we arrange.
Not everything that looks commercial qualifies. Some properties, such as mixed-use buildings, may not meet the business real property test, so we check the property against the rules and lender policy before you sign a contract.
If your fund already has an SMSF commercial loan, our mortgage brokers in Albury Wodonga can review it and see whether a refinance could improve the rate or terms.
Renting vs Owning Through Your SMSF
For a business owner, rent is a fixed cost. Here is what changes when your fund owns the premises instead of an outside landlord.
| Renting From a Landlord | Your SMSF Owns the Premises |
|---|---|
| Rent builds someone else's wealth | Rent goes into your own super fund |
| Rent is a deductible business expense | Rent is still a deductible business expense |
| Landlord decides on renewals and increases | Lease set at market rate, with security of tenure |
| No ownership of the property | Fund owns it, held in a holding trust until repaid |
| Rental income taxed in the landlord's hands | Rent generally taxed at 15% inside the fund, or potentially 0% in pension phase. Members with super balances over $3 million may pay extra tax from 1 July 2026 |
Eligible Commercial Properties
Most standard commercial property types are accepted by SMSF lenders, including:
- Industrial and trade: warehouses, factories, workshops and storage units
- Offices: professional suites and office space
- Retail and hospitality: shopfronts, showrooms and cafes
- Medical and allied health: GP clinics, dental practices, physio rooms and pharmacies
- Rural: some farmland used in a primary production business, with select lenders
Mixed-use properties, vacant land for development and specialised assets are harder to finance and may not meet the rules. We check the property upfront so you do not risk a deposit on one that will not pass.
Who Is Eligible for an SMSF Loan
Lenders look at your fund as closely as the property. As a general guide, your fund will usually need:
Registered SMSF
A properly established SMSF, registered with the ATO, with its own ABN and bank account
Trust Deed That Allows Borrowing
A trust deed that allows borrowing through a limited recourse borrowing arrangement
Investment Strategy
An investment strategy that supports buying the property
Accepted Trustee Structure
A trustee structure lenders accept, with many preferring a corporate trustee
Enough in the Fund
Enough in the fund to cover the deposit, purchase costs and a buffer, often with a minimum fund balance set by the lender
Eligible Property
A commercial property that meets the business real property test and the lender's policy
Repayments Covered
Rent and contributions that can comfortably cover the repayments
Each lender sets its own rules, so treat this as a starting point. We check your fund against current lender policy before you apply.
What Lenders Assess
Fewer lenders offer SMSF commercial loans, and they apply extra checks. Knowing what they focus on helps you avoid delays.
Fund Balance and Liquidity
Most lenders cap SMSF commercial loans at around 70% to 80% of the property value, so the fund needs the deposit plus stamp duty and costs. Many also want a cash buffer left in the fund after settlement.
Lease and Rental Income
A signed lease at market rent, backed by an independent valuation, carries a lot of weight. Where the tenant is your own business, lenders may also look at its financials.
Contributions
Regular concessional contributions from members add to the fund's ability to service the loan, and lenders count them.
Trust Deed and Structure
The deed must allow borrowing and the investment, the investment strategy must support it, and the holding trust must be set up correctly. Lenders check all three.
Working Out the Deposit and Repayments
The lending limits above shape how much your fund needs to bring and how the loan gets repaid. Here's how the numbers usually come together:
The Deposit and Purchase Costs
On an $800,000 commercial property at a 70% LVR, the fund would borrow $560,000 and need $240,000, plus stamp duty, legal and valuation fees, and the cost of setting up the holding trust. All of this comes from the fund's own balance, so members may need to plan their contributions ahead of time, within the contribution caps.
Keeping a Buffer
After the deposit and costs are paid, lenders want money left in the fund so it can keep paying the loan through a vacancy or a quiet patch. Plan for this from the start rather than putting every dollar into the purchase.
How Repayments Are Covered
The loan is repaid from inside the fund, using the rent from the property plus members' super contributions, less running costs such as the annual audit, accounting and insurance. Where your own business is the tenant, the rent depends on that business doing well, so lenders may check its financials, and some also consider members' personal income.
What Strengthens the Application
A signed lease at market rent backed by an independent valuation, steady contributions, a healthy buffer and a fund with a clean audit history all help.
Rules and Risks
These are the ones we always talk through before you commit.
Arm's Length Leasing
A lease to your own business must be on commercial terms: market rent, paid on time, under a written lease. Rent holidays or discounts can breach super rules.
Sole Purpose Test
The property must be held to provide retirement benefits. Using it for personal benefit outside a proper lease is not allowed.
Limits on Improvements
Borrowed money cannot be used to improve the property in a way that changes its character. Repairs and maintenance are fine, and the fund can pay for some works from its own cash.
Vacancy, Costs and Concentration
If your business moves or closes, the fund may face a vacancy with repayments still due. SMSF loans also carry higher rates and fees than standard commercial loans, plus ongoing audit and admin costs, and one large property can leave the fund poorly diversified.
What You'll Need
Having these on hand makes the first conversation far more useful.
- SMSF trust deed and investment strategy
- Fund members and trustee structure (individual or corporate)
- Last two years of fund financial statements and member balances
- Property details, plus any existing or proposed lease
- Business financials, if your own business will be the tenant
- Contact details for your accountant or financial adviser
Requirements vary by lender. Missing a few is fine. Reach out and we will confirm what your lender needs.
How the SMSF Loan Process Works
Here's what the process usually looks like, from the first conversation to settlement:
Step 1
Get Advice First
Your licensed financial adviser and accountant confirm whether buying commercial property through your SMSF suits you, and help set up the fund or a corporate trustee if needed.
Step 2
Check Your Fund Against Lender Policy
We review your trust deed, investment strategy and fund balance against the lenders that offer SMSF commercial loans, and look at pre-approval where it's available.
Step 3
Set Up the Holding Trust
The holding (bare) trust and its trustee need to be in place before you sign a contract, usually arranged by your accountant or solicitor.
Step 4
Find the Property and Sign the Contract
The contract must be in the right name, usually the holding trustee, so check the wording with your solicitor before you sign.
Step 5
Valuation, Lease and Formal Approval
The lender values the property, reviews the lease at market rent, and issues formal approval.
Step 6
Settlement
The fund pays the deposit and costs, the loan settles, and the property is held in the holding trust.
Step 7
After Settlement
Rent is paid into the fund, repayments come out of the fund, and the annual audit continues. We review the loan over time to make sure it still suits.
Most banks have stepped back from SMSF lending. Our job is knowing which lenders still do it and setting the structure up right from day one.
Fund and structure review
We review your trust deed, investment strategy and fund position against lender requirements before anything is lodged.
Matching you to SMSF lenders
Rates, fees and LVRs vary widely between the specialist lenders. We compare them and focus on the ones suited to your fund and property.
Working alongside your advisers
We coordinate with your accountant, adviser and solicitor so the holding trust, lease and loan all line up.
Through to settlement and beyond
We keep the application moving to settlement, then review the loan over time to see if a refinance could save the fund money.
Why Trustees Choose Us
Plenty of brokers arrange loans. Fewer are comfortable with commercial lending inside super.
- Local to Albury and Wodonga, and familiar with commercial property in the region
- Experience in business, commercial and agricultural lending
- Access to the specialist lenders active in SMSF commercial lending
- Plain-language explanations and no-pressure advice
- Works alongside your accountant and adviser
- A long-term finance partner for you and your business
There is no obligation. Book a chat whenever you are ready.
Signs It May Suit You
- You own a business and rent your premises
- You plan to stay in your premises for the long term
- You run an SMSF, or are setting one up
- Your fund has the balance for a deposit and costs, with a buffer left over
- Your accountant or adviser has raised it as part of your strategy
- You already hold an SMSF commercial loan that has not been reviewed in two years or more
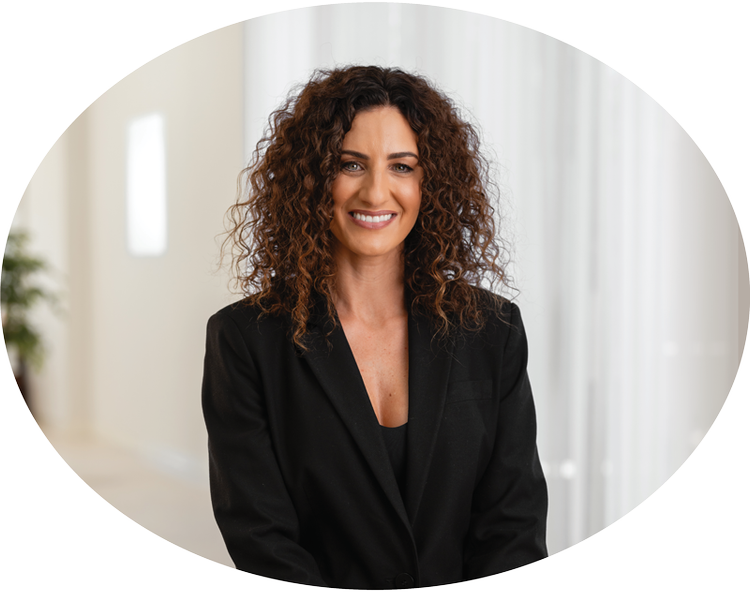
Hi there, I'm Kirsty
Kirsty has spent over 18 years helping clients reach their property goals. She takes the time to understand each situation and gives guidance without jargon or pressure, whatever the structure behind the purchase.
Book a chat with Kirsty
Hello, I'm Sophie
With 12 years in finance, Sophie brings extensive expertise in business and residential lending. She specialises in agricultural, commercial, equipment finance, and home loans, with tailored advice to suit each client's needs.
Book a chat with SophieSee what local clients say about us
We are proud of the relationships we build across Albury and Wodonga. You can read what clients have to say, or leave a review of your own, on our Google Business Profile.
“I highly recommend Loan Street Finance, they are professional, honest and don't promise anything they can't deliver. They know their profession inside and out. I am very grateful that they were recommended to me and I have no hesitation in recommending them to others.”
“Kirsty has access to many lenders and therefore can find you the best deal. Kirsty's attention to detail and tailored advice make loan street our top choice for all our lending needs. Highly recommended”
“I have used Kirsty and the team more than once, and the experience has always been great. Plenty of options, great rates and a wealth of knowledge. Would recommend Loan Street Finance in an instant.”
SMSF commercial loan questions, answered.
Can my SMSF buy my business premises?
What types of properties are eligible?
How much can my SMSF borrow?
Can I refinance my existing SMSF commercial loan?
Can my SMSF get a loan for residential property?
Does using a broker cost me anything?
What does an SMSF loan broker do?
Do I need a corporate trustee for an SMSF loan?
The information on this page is general in nature and does not take into account your personal circumstances, including your financial situation, your goals, your fund, or the particular property you have in mind. Superannuation, tax, and lender rules can change over time and vary depending on your situation. Borrowing through an SMSF is complex, so before making any decisions speak with a qualified professional, such as an accountant or licensed financial adviser, who can look at your individual circumstances.