
Mortgage Broker for the Self-Employed: get approved on your income.
Working for yourself should not mean fighting the bank for a loan. We know how lenders read business income, which ones say yes, and how to present your figures so your real earning power comes through.
Get in touch
A self-employed mortgage broker who backs business owners.
Running your own business takes grit, and it is frustrating when that same independence makes a lender hesitate. Income that rises and falls, two sets of tax returns, and add-backs a generalist does not understand can all slow things down, even when your business is doing well.
The good news is that plenty of lenders are comfortable with self-employed borrowers once your income is presented well. With the right lender from the start, home loans for business owners are far more straightforward.
Working with a mortgage broker for self-employed borrowers means you have someone who knows how to turn your financials into an approval. A good mortgage broker in Albury & Wodonga will read your returns, find the add-backs, and match you to a lender that says yes. And if someone close to you earns a salary instead, a broker for teachers helps them along similar lines.
From a sole trader to a company director, no two self-employed situations are the same. We take the time to understand your business and how you draw your income, then guide you through the options without the pressure.
Why Self-Employed Loans Feel Harder
It is not your imagination. Self-employed lending genuinely involves a few more hurdles than a salaried application. Knowing what they are takes much of the sting out of them:
Income That Varies
Business income can swing from year to year, and lenders like to see it is reliable before they commit. A steady or growing pattern helps, and the right lender can look past a single quieter year to the bigger picture.
More Paperwork
Where a salaried borrower hands over payslips, you will usually need tax returns and financials, often for two years. It is more to gather, but with your records in order it becomes far less daunting than it first appears.
Add-Backs Lenders Miss
Your taxable income is often lower than your real earning capacity, thanks to deductions a lender can add back. A generalist may miss these, leaving you looking like you earn less than you do, which is exactly where expertise pays off.
Wrong Lender Choice
Lenders vary enormously in how they treat self-employed income, so going to the wrong one can mean a needless knock-back. Much of the difficulty disappears simply by starting with a lender suited to your situation.
Full Doc or Low Doc Loans
Two common paths for the self-employed are a full doc loan and a low doc loan, and which suits depends on your records. Seeing them side by side helps you understand where you fit.
| A Full Doc Loan | A Low Doc Loan |
|---|---|
| Tax returns and financials provided | Alternative evidence of income used |
| Widest lender choice and sharpest rates | Fewer lenders, often different terms |
| Suits established, documented income | Suits incomplete or recent records |
| Usually two years of figures | Where full returns are not yet available |
| The standard self-employed path | A useful path in specific situations |
How Your Income Is Documented
Self-employed lending offers a few documentation paths, and the right one depends on what records you have. A useful general read is the government's guide to home loan basics, and the main options are:
A Full Doc Loan
With full documentation, you provide tax returns and financials, usually for two years, and access the widest range of lenders and the sharpest rates. It is the standard path where your records are complete and your income is well established.
A Low Doc Loan
A low doc home loan suits borrowers who cannot yet provide the full set of returns, relying instead on alternative evidence of income. It can open a door when full documentation is not available, though it may come with different terms, so it is worth weighing carefully.
An Alt Doc Loan
Alternative documentation uses items such as business bank statements or an accountant's declaration to verify income. With the right lender, it gives flexibility for the self-employed whose situation does not fit a standard mould.
Low Doc Loans and Alternatives
If you can't provide two full years of tax returns yet, you still have options. Here's how they compare:
One Year Full Doc
Some lenders accept a single year of tax returns and financials, especially if you worked in the same industry before going out on your own. Where it's possible, this usually gets you better rates and terms than a low doc loan.
BAS-Based Low Doc
Some lenders use your recent Business Activity Statements (BAS) to verify your turnover, often covering 6 to 12 months or more, usually alongside a declaration from your accountant.
Bank Statement Loans
Some specialist lenders verify your income from business bank statements, typically covering 6 to 12 months of trading.
An Accountant's Declaration
A letter from your accountant confirming your income can support a low doc or alt doc application with lenders that accept it.
What to Expect
Low doc loans usually come with lower maximum LVRs, often up to around 80%, higher rates and fees, and fewer lenders to choose from. You'll still need to show you can comfortably afford the repayments.
Moving to Full Doc Later
Once your tax returns are lodged, refinancing to a full doc loan may get you a sharper rate. We can review it with you when the time is right.
Who This Suits
Eligibility depends on the lender and your situation, so the only way to be sure is to have it checked. As a general guide, self-employed lending tends to suit borrowers who can show a few things:
- An active Australian Business Number (ABN), and Goods and Services Tax (GST) registration where it applies
- A trading history, ideally a year or two, though some lenders are flexible
- Tax returns and financials, or alternative income evidence
- A credit history that is in reasonable shape
- A deposit, even a modest one in some cases
- A property the lender is comfortable with
Each lender takes its own view of self-employed income and how long you must have traded, so treat these as a starting point rather than a fixed list. We can check your position against the lenders most likely to suit you.
Sole Trader vs Company: How Your Structure Affects Your Loan
How your business is set up changes which documents a lender wants and how your income is worked out. As a general guide:
| Sole Trader | Company | |
|---|---|---|
| How your income shows up | Business profit is your personal income, on your own tax return | You're paid wages, dividends or both, and the company may keep some profit |
| What lenders assess | Your net profit plus fair add-backs | Your wages and dividends, and some lenders also count your share of company profit |
| Documents | Personal tax returns and notices of assessment | Company and personal tax returns, plus company financial statements |
| Things to watch | Large deductions can lower your assessable income | Profit kept in the company may not count unless the lender includes it |
Partnerships and Trusts
In a partnership, lenders look at your share of the partnership's income. With a trust, they usually look at the distributions paid to you, and some also consider the trust's profit if you control it. Both need the entity's tax returns as well as your own.
Your ABN and GST
Most lenders want your ABN registered for at least one to two years, though some will consider less if you worked in the same industry before. Being registered for GST, where your turnover requires it, also helps show an established business.
Your structure should be set for tax and business reasons with your accountant. As your local mortgage broker in Albury Wodonga, we then match you to lenders that suit it.
What Lenders Look at for the Self-Employed
Lenders want confidence that your business income is genuine and likely to continue. Knowing what they weigh up helps you prepare:
Your Trading History
How long you have been trading, and how steady your income has been, both matter a great deal. A longer, consistent history reassures a lender, while a newer business may need the right lender and a strong recent year.
Your Business Financials
Lenders examine your tax returns and financials to understand what the business genuinely earns and what flows through to you. Clear, current records make this far easier and help your case considerably.
Your ABN and GST Registration
How long your ABN has been active, and your GST registration where relevant, feed into a lender's view of your business. Longer registration tends to help, signalling an established operation rather than a brand-new one.
Your Personal Commitments
Alongside the business, lenders weigh your personal debts and living costs against the income you draw. Keeping personal commitments tidy, and any business and personal finances sensibly separated, makes the whole picture easier to assess.
Self-Employed Lender Policy by Income Type
Each lender has its own policy on self-employed income, and the type of income you earn shapes how it's assessed. As a general guide:
| Income Type | How Lenders Commonly Assess It |
|---|---|
| Sole trader profit | Net profit from your tax returns plus add-backs, often averaged over two years, or the lower year if income has dropped |
| Partnership income | Your share of the partnership's net income, plus add-backs relating to your share |
| Company wages | The wages your company pays you, shown on your personal tax return |
| Company profit and dividends | Some lenders count your share of the company's net profit, including retained profits, instead of dividends, so income isn't counted twice |
| Trust distributions | Distributions paid to you from the trust, and some lenders look at the trust's profit if you control it |
| ABN contractor | Some lenders treat contractors working for one main client more like employees, assessing the contract rate with a shorter history |
| Newer business | Often one year of full financials, especially with prior experience in the same industry |
Lender policies vary and change often, so treat this as a starting point. We check your income against current policy across our lender panel.
Boosting Your Assessable Income
The income a lender assesses is often higher than your taxable income once add-backs are applied, and getting this right is central. A few things make the difference:
Common Add-Backs
Depreciation, additional superannuation, interest, and genuine one-off expenses can often be added back to your income. A lender comfortable with the self-employed will count these where they are fair, lifting your assessed earnings.
Strong Latest Year
If your most recent year is your best, some lenders will weigh it more heavily than an average of the past two. Choosing a lender that recognises an improving business can let your numbers work harder for you.
Clean, Up-to-Date Returns
Lodging your tax returns promptly and keeping your financials current avoids one of the most common delays for self-employed borrowers. Being up to date keeps every option open when you are ready to apply.
Right Lender's Rules
Each lender applies its own rules on which add-backs it accepts and how it averages your income. Matching your figures to a lender whose rules suit them is a big part of getting the strongest result.
Patience for the Process
Self-employed applications can take a little longer to assess than a simple salaried one, so a touch of patience helps. Getting your figures in early and answering questions promptly keeps everything moving as smoothly as it can.
Documents Needed for a Self-Employed Home Loan
The documents you need depend on how your business is set up and whether you're going full doc or low doc. As a general guide:
| Your Situation | Documents Lenders Usually Ask For |
|---|---|
| Everyone | Photo ID, your ABN details, recent business and personal bank statements, evidence of your deposit, and details of any debts |
| Sole trader | Your last two years of personal tax returns and ATO notices of assessment |
| Partnership | The partnership's tax returns and financials, plus your personal tax returns and notices of assessment, usually for two years |
| Company | The company's tax returns and financial statements, plus your personal tax returns and notices of assessment, usually for two years |
| Trust | The trust's tax returns and financials, your personal returns showing distributions, and sometimes the trust deed |
| Low doc | Business Activity Statements (BAS), business bank statements and often a declaration from your accountant, instead of full returns |
Many lenders also ask for an ATO statement showing you're up to date with tax, or that any debt is on a payment plan. Missing a few items is fine. Get in touch and we'll confirm exactly what your lender will need.
For the self-employed, the value of a broker shows in the practical work: turning your financials into a genuine approval.
Understanding your business
We start by getting a real sense of how your business runs and how you draw your income, since that shapes everything. A clear picture often reveals more borrowing power than you expected.
Finding the right lender
Lenders differ hugely in how they treat self-employed income, so we focus on those genuinely suited to your situation. Starting with the right lender avoids needless knock-backs and the dent they leave on your file.
Maximising your add-backs
We work through your financials to identify the add-backs that fairly lift your assessable income. Getting these recognised can be the very thing that turns a marginal application into a comfortable one.
Presenting your income
How your figures are framed and explained to a lender matters as much as the figures themselves. We present your income clearly, so a lender sees the genuine, ongoing strength of your business.
Reviewing year on year
As your business grows and your returns improve, we stay in touch and revisit the loan when it makes sense. The relationship does not end at settlement, and there is never any pressure to act before it suits you.
Why the Self-Employed Choose Loan Street Finance
Plenty of brokers can arrange a loan, but fewer enjoy untangling a self-employed home loan the way we do. What brings business owners our way is that we make your income work for you rather than against you.
- Based in Albury and Wodonga, working with local business owners
- Comfortable reading tax returns, financials, and structures
- Clear on which lenders say yes to self-employed income
- Add-backs found and presented so they count
- Full doc, low doc, and alt doc paths all on the table
- Here as your business grows, not just for this one loan
If that resonates with what you need, we are ready when you are. There is no obligation at all, just a friendly conversation about turning your income into an approval.
Considerations for Newer Businesses
If your business is relatively young, a few extra points are worth bearing in mind, since they shape your options:
A Short Trading History
Many lenders prefer two years of figures, but some will consider one strong year, particularly with a solid track record in the same field beforehand. Knowing which lenders are flexible here can open a door sooner than you expect.
A Growing Income
A business on an upward trend can be appealing, even if the history is short, provided the growth looks genuine and sustainable. The right lender will take a forward-looking view rather than focusing only on the past.
A Recent ABN
A newly registered ABN can make some lenders cautious, though prior experience in your industry often counts in your favour. Presenting that background well helps bridge the gap.
An Emerging Track Record
Every established business was once new, and lenders know it, so a short but solid record is not a dead end. Tidy, consistent figures from the outset make it far easier to demonstrate your progress.
Signs It May Be Worth a Look
A perfect moment rarely arrives, but a few signs can suggest it is worth thinking about:
- You run your own business, as a sole trader or through a company
- A previous lender struggled with your self-employed income
- Your taxable income looks lower than what you really earn
- You have a year or two of returns, or strong recent figures
- You are weighing your first home, an upgrade, or an investment
- You would like someone to turn your numbers into an approval
Hi there, I'm Kirsty
Kirsty has spent over 18 years helping people achieve their home ownership dreams. She takes the time to understand each situation and provides guidance without jargon or pressure, whatever the structure behind the purchase.
Book a chat with Kirsty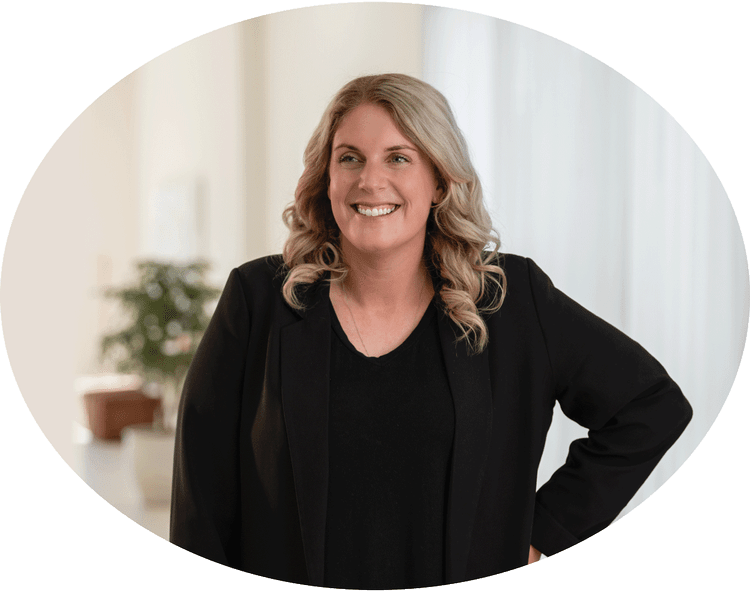
Hello, I'm Sophie
With 12 years in finance, Sophie brings extensive expertise in business and residential lending. She specialises in agricultural, commercial, equipment finance, and home loans, with tailored advice to suit each client's needs.
Book a chat with SophieSee what local clients say about us
We are proud of the relationships we build across Albury and Wodonga. You can read what clients have to say, or leave a review of your own, on our Google Business Profile.
Read our Google reviews
Self-employed mortgage broker questions, answered.
Can I get a home loan if I am self-employed?
Does using a broker cost me anything?
Do I need two years of tax returns?
What is a low doc home loan?
What are add-backs, and why do they matter?
My business is new. Can I still borrow?
Will going to my own bank be easier?
How much can I borrow when self-employed?
What does a mortgage broker for self-employed borrowers do?
Is it better to be a sole trader or a company for a home loan?
How much deposit do I need for a low doc loan?
Can I get a home loan if I owe the ATO?
The information on this page is general in nature and does not take into account your personal or business circumstances, including your financial situation, your goals, or the particular property you have in mind. Lender policies on self-employed income, low doc lending, and interest rates can change over time and vary between lenders. Before making any decisions, it is a good idea to speak with a qualified professional, such as your accountant, who can look at your individual circumstances and give advice that genuinely fits you.